What to Do Immediately After a Suspicious Card Transaction
A suspicious card transaction can appear in several forms: an unfamiliar merchant name, a charge in a foreign currency, a duplicated amount, or a small test payment followed by larger ones. Regardless of the specific pattern, the first minutes and hours after noticing the activity tend to matter most for limiting exposure and preserving the information a bank or card issuer may later request. The process is less about panic and more about sequence — knowing which actions come first, which can wait, and which records are worth keeping.
This overview describes a general framework that cardholders in the United States can adapt to their own situation. It covers freezing or locking the card, contacting the financial institution through verified channels, and assembling documentation that supports a dispute. Because each issuer, card network, and account type follows its own procedures, the details below are informational rather than prescriptive, and the specific steps should always be confirmed with the institution that issued the card.
The underlying principle is transparency: acting deliberately, keeping a written record of what was done and when, and relying on official channels rather than informal workarounds. That approach tends to make later conversations with a bank, a merchant, or a dispute team more straightforward, even when the final outcome depends on factors outside the cardholder’s control.
Freezing or Locking the Card as a First Step
Most major card issuers in the United States provide a freeze or lock function inside their mobile app or online banking portal. This feature typically stops new authorizations from being approved while leaving the account itself open, which means recurring bills and existing subscriptions may or may not continue depending on how the issuer implements the control. The distinction between a temporary lock and a permanent block is worth understanding before tapping either option, because a full block usually requires a replacement card and a new card number.
Freezing the card is generally the fastest way to interrupt further unauthorized activity without waiting on a phone queue. The action is usually reversible, and many issuers allow the cardholder to unfreeze the card once the situation is clarified. It is helpful to note the exact time the freeze was applied, since that timestamp can later help distinguish transactions that occurred before the lock from any that were attempted afterward. Some institutions also send a confirmation email or in-app notice, which is worth saving.
If the card is a physical card that appears to have been lost or copied, a freeze may be paired with a request for a new card number. In that case, the cardholder should expect to update stored payment details with merchants, subscription services, and digital wallets. The timing of a replacement varies by issuer and by mail delivery, and it may be useful to ask whether a digital version of the new card can be issued immediately for use while the physical card is in transit.
- Use the official issuer app or website rather than a link received by text or email.
- Record the date and time the freeze was activated.
- Check whether the lock affects recurring payments or only new purchases.
- Ask whether a replacement card number will be issued and when.
Contacting the Bank Through Verified Channels
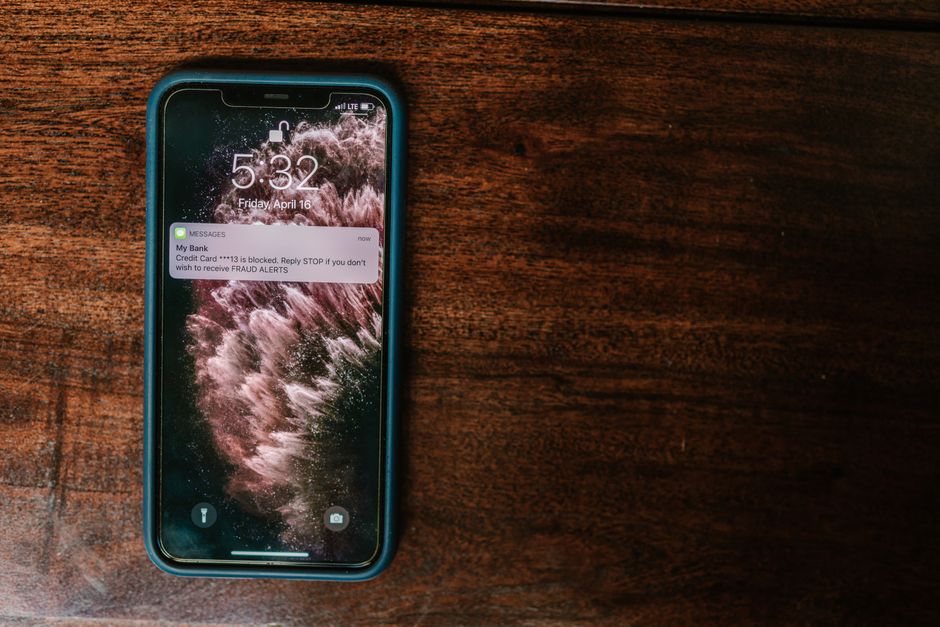
Once the card is secured, the next step is to reach the financial institution using a phone number printed on the back of the card or listed in the official app. Scam messages often imitate fraud alerts and ask the recipient to call a number or click a link, so verifying the contact channel independently is an important safeguard. A representative can confirm whether the transaction is genuinely unrecognized, place additional controls on the account, and explain the issuer’s specific dispute process.
During the call, it helps to have the account information and the transaction details ready, including the merchant name, the amount, the date, and any reference number visible in the transaction history. The representative may ask whether the card is in the cardholder’s possession, whether any authorized users could have made the purchase, and whether the card details were recently used on an unfamiliar website. Answering factually and without speculation tends to keep the process efficient, and the cardholder can request a reference or case number for the conversation.
It is reasonable to ask what the next steps will be, how long a provisional credit might take if one is offered, and whether the issuer requires a written statement or a signed form. Some institutions accept a dispute entirely by phone, while others route the case through an online form or a mailed affidavit. Because policies differ, confirming the exact requirements during the call reduces the chance of a delay caused by missing paperwork. The issuer’s instructions should take precedence over general guidance found elsewhere.
Documentation is most useful when it is created close to the event, while timestamps, merchant names, and reference numbers are still easy to verify.
Collecting Evidence for a Dispute
Evidence gathering can begin in parallel with the bank contact, since much of the material is already available in the account’s transaction history. A dispute is generally easier to evaluate when the cardholder can show a clear timeline: when the card was last used legitimately, when the suspicious charge appeared, and when the card was frozen. Screenshots of the transaction listing, with dates and amounts visible, are commonly requested and are simple to capture before any entries are updated or removed from view.
Beyond the transaction record, useful material may include confirmation emails or receipts from legitimate purchases, any communication with the merchant if one was attempted, and notes from the call with the bank. If the suspicious charge relates to a subscription or a service the cardholder does recognize, a cancellation confirmation can help clarify the boundary between an authorized and an unauthorized charge. Keeping these items in a single folder, whether digital or physical, makes it easier to respond when the issuer asks for additional information.
It is also worth reviewing other accounts and cards for similar activity, since compromised card details are sometimes tested across multiple institutions. Changing passwords on shopping accounts and enabling transaction alerts can provide earlier warning if further attempts occur. These measures are preventive in nature, and their effectiveness depends on how the compromise happened, so they are best treated as sensible hygiene rather than a guarantee of protection.
- Capture screenshots of the suspicious transaction with date, amount, and merchant name.
- Save any fraud alert emails, texts, or app notifications.
- Note the date, time, and reference number of each call with the issuer.
- Retain receipts or confirmations for nearby legitimate purchases.
- Keep a short written timeline of what happened and when.
Understanding the Dispute Process and Its Limits
Card disputes in the United States are generally handled under the issuer’s own procedures and, for consumer credit cards, under federal rules that set timelines for investigation and provisional credit. The specific protections can differ between credit and debit products, and they may depend on how quickly the cardholder reports the issue. A representative can clarify which rules apply to a given account, and the issuer’s written dispute summary usually outlines the expected timeline.
The outcome of a dispute is not determined by any single action. It may depend on the evidence provided, the merchant’s response, the card network’s rules, and the issuer’s assessment of the circumstances. For that reason, the goal of the immediate steps is to preserve options and create a clear record rather than to force a particular result. Professional guidance from the issuer or, where appropriate, a qualified advisor can help interpret the specific situation.
SecurePay Advisors notes that a calm, documented approach tends to serve cardholders well throughout the process, especially when several parties are involved. Following up on the case at reasonable intervals, responding to requests for information promptly, and keeping copies of everything submitted are practical habits that support continuity. The broader lesson is procedural: secure the card, verify the channel, contact the institution, and preserve the evidence, while recognizing that each case unfolds according to its own facts.